Your Low Rate Is an Asset. Here Is How to Use It.
.jpg)
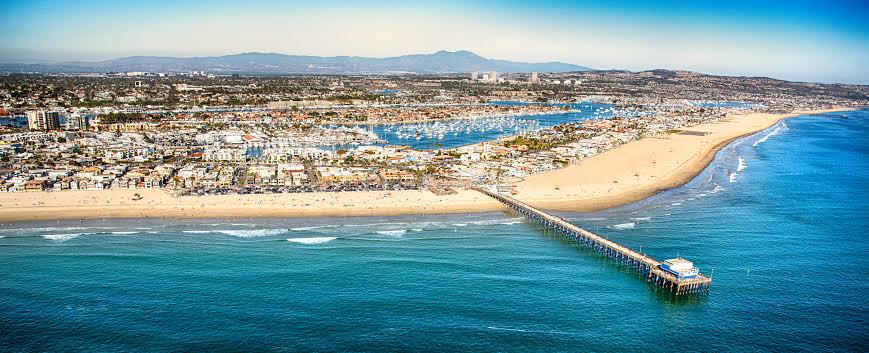
On September 16th, the Federal Reserve raised interest rates for the first time since 2023. The 30-year fixed mortgage rate hit a one-year high and sits at 7.03% as of this writing. If you purchased or refinanced during COVID at or near 3%, the gap between your current rate and a new mortgage has never been wider. For most homeowners that feels like a reason to stay put. It might actually be your greatest financial advantage right now, if you use it correctly.
What a Mortgage Rate Is and Why It Matters
A mortgage rate is the interest a lender charges you to borrow money to buy a home, applied monthly to your loan balance. For buyers, a higher rate means a higher payment and fewer qualified competitors in the market. For homeowners, your existing rate is a financial asset sitting on your balance sheet. For renters, rising rates tighten housing supply and push monthly rents higher. It affects everyone, whether you are actively transacting or not.
The National Story vs. the Coastal OC Story
When national media reports on 7% mortgage rates, they are describing the impact on a median-priced American home at roughly $400,000. A buyer financing $320,000 at 7% pays approximately $2,129 per month in principal and interest. That is a real number for a large portion of the country, and the affordability strain is genuine.
Coastal Orange County is a different conversation entirely.
The buyers actively purchasing in Laguna Beach, Newport Beach, Dana Point, and San Clemente are not the buyers the national headlines are written for. The majority of transactions in these markets involve substantial down payments, significant existing equity, and in many cases all-cash offers. These are not buyers whose purchasing decision hinges on whether the 30-year fixed is 6.5% or 7%.
The COVID Rate Hangover
Hundreds of thousands of California homeowners locked in rates at or near 3% between 2020 and 2021. With today's rate at 7.03%, giving that up to buy something new means taking on a mortgage that costs more than double per dollar borrowed. Most homeowners feel stuck. The smarter move is to recognize that rate as leverage, not as a cage.
"The right move for you is the right move — even when it is not the move that generates a commission." — Clay Smith
A Strategy Worth Considering
Rather than staying put or selling, consider a third option: convert your primary residence into a rental, pocket the monthly income, and rent a home that better fits where you are in life right now.
The coastal OC rental market is as strong as it has been in years. Buyers who are priced out or waiting on rates are driving demand for quality rentals, pushing inventory down and monthly rents up. A well-maintained home in Laguna Beach, Dana Point, or Newport Beach can generate meaningful monthly income while your low-rate mortgage stays intact and your equity continues to build.
In the meantime, renting gives you flexibility. Want to be closer to the water? Try a different neighborhood? Upsize for a growing family or downsize now that the kids are gone? You can do all of that without permanently committing to a new purchase at today's rates. When the rate environment shifts and conditions align with your long-term goals, you make the move from a position of strength rather than necessity.
This is one of the most underutilized strategies available to coastal OC homeowners right now. It does not work for everyone, but for the owner who has equity, a low rate, and a lifestyle that is ready for something different, it is worth a serious conversation.
Last thing worth knowing. Most agents who have your contact information would be pushing you to list — because a sale means a commission and a commission means money. I understand that. But my goal with everything I put out, this newsletter, my blog, my social content, is to give you information that is actually useful, not a sales pitch dressed up as advice. If renting your home and waiting makes more sense for your situation than selling right now, that is what I am going to tell you.
Why Your Property's Current Value Matters More Than Ever
Before any of this is possible, you need to know what your property is actually worth today. An accurate current valuation is the starting point for every decision that follows: whether to hold, rent, or eventually sell.
- Your 3% rate is a financial asset — treat it like one, not like a constraint.
- The coastal OC buyer pool is different from the national median. Rate headlines are not written for this market.
- The rental strategy preserves your low rate while generating income and giving you flexibility to move without a permanent commitment at today's rates.
- Rental demand is high across Laguna Beach, Newport Beach, and Dana Point — quality homes do not sit.
- Know your current value before making any decision. An outdated estimate leads to the wrong move.
- The right agent tells you what makes sense for your situation, not what generates a transaction for them.
The Bottom Line
A 3% mortgage in a 7% rate environment is not a reason to stay stuck. It is a position of strength that most homeowners are not using. If your life is ready for something different and your equity is real, there is a path forward that does not require you to give up the rate you earned. To understand where your home's value sits right now, reach out below.
Clay Smith · BonLife Real Estate · DRE #02425337
This article is intended for informational purposes and does not constitute financial or legal advice. Mortgage rate data referenced as of September 16, 2026.
What Does This Mean for Your Property?
If you own a home in coastal OC and want a straight read on your current position, reach out. I will give you an honest answer, not a pitch.
Contact Clay